5 Questions to Ask Your Financial Advisor Before You Retire
Patrick Thompson
You may have a financial advisor managing your investments. But is someone helping you coordinate all the decisions that will shape your retirement?
Tax, Medicare and Social Security rules change. This article reflects information as of October 2026.
The Short Answer: 5 Questions to Ask Before You Retire
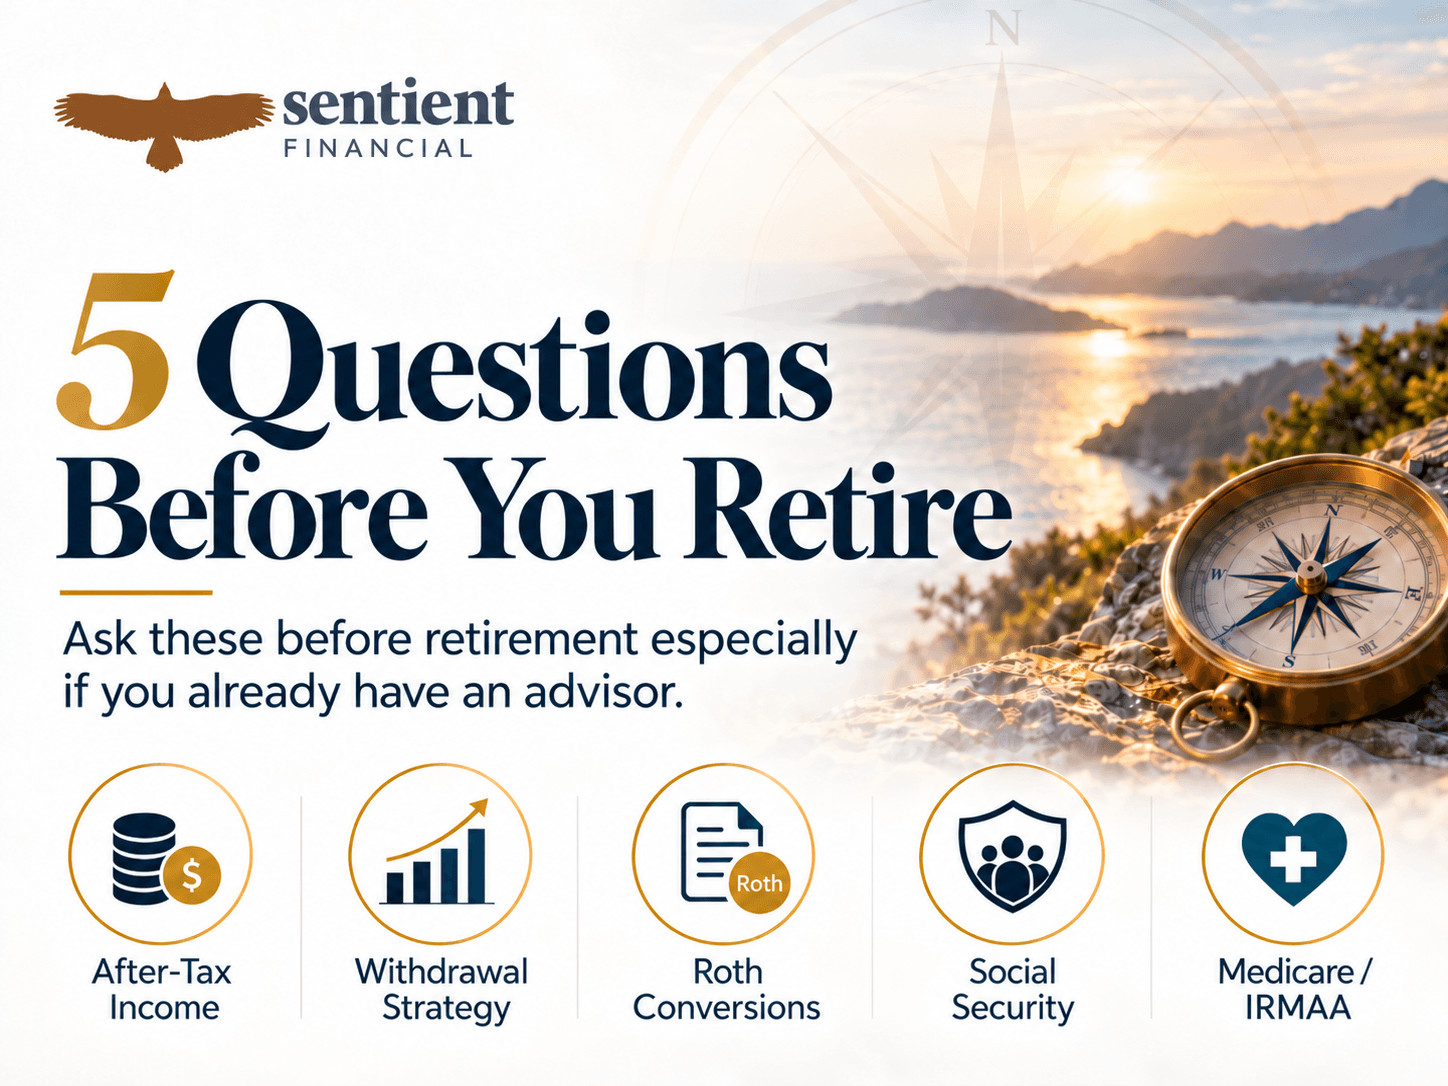
Before you retire, ask your advisor these five questions. Each one affects the others, so the answers work best as part of one coordinated plan.
- How much monthly income will I actually have after taxes?
- Which accounts should I withdraw money from first?
- Should I be considering Roth conversions before retirement?
- When should I claim Social Security, and how does that decision affect my other income?
- Could my retirement income decisions increase my Medicare premiums?
You've spent decades saving, investing, and building your retirement nest egg. Maybe you've worked with the same financial advisor for years. Your portfolio is diversified, you receive regular performance reports, and your investments seem to be doing what they're supposed to do.
That's a good start.
But as retirement gets closer, the questions become very different.
It's no longer just about how much your investments are earning. It's about how those investments will support your lifestyle, how much you'll pay in taxes, when you should claim Social Security, and how to make the different pieces of your financial life work together.
Your portfolio has a new job: providing retirement income. (We cover that shift in Your Portfolio Has a New Job.)
Whether you're five years from retirement or preparing to leave work next year, here are five questions your financial advisor should be able to answer.
1. How Much Monthly Income Will I Actually Have After Taxes?
Your advisor should be able to show you an estimate of your monthly income after taxes, broken out by source, and how that estimate could change under different market, inflation, and spending assumptions.
Knowing your portfolio is worth $1 million or $2 million is one thing. Understanding how much of that money you can reasonably spend each month in retirement is something entirely different.
Your retirement income might come from several sources:
- Social Security benefits
- Pensions
- Traditional IRAs and 401(k)s
- Roth accounts
- Taxable investments, including dividends and interest
But those sources aren't all taxed the same way. (For a deeper look, read how retirement income is taxed and why it's higher than you expect.)
A withdrawal from a traditional IRA generally creates ordinary taxable income. Qualified Roth IRA withdrawals are tax-free. Selling investments in a taxable brokerage account may produce capital gains, while a portion of the proceeds may simply represent your original investment.
That means two retirees with identical portfolio balances could have very different amounts available to spend after taxes.
What your advisor should help you understand: Your expected retirement income after taxes, where that income will come from, and how your plan could hold up under different market conditions, inflation assumptions, and spending needs.
A retirement income plan should go beyond a portfolio balance and an assumed rate of return. It should help you understand what your savings can realistically support.
2. Which Accounts Should I Withdraw Money From First?
The best withdrawal order depends on your tax bracket, future required minimum distributions (RMDs), how much of your Social Security is taxed, and your Medicare premiums. There is no universal rule.
Here's a question that doesn't get nearly enough attention.
Let's say you've accumulated $1.5 million across a traditional IRA, a Roth IRA, and a taxable brokerage account. (Hypothetical example for illustration only. Your numbers and results will differ.)
When retirement begins, where should your monthly income come from?
Some retirees automatically withdraw from their taxable accounts first, followed by tax-deferred accounts, and leave their Roth accounts for last.
That approach might make sense in certain circumstances, but it's not a universal rule.
The order in which you withdraw money can affect your tax bracket, future RMDs, the taxation of Social Security benefits, and even your Medicare premiums. (See our guide to the most tax-efficient order to withdraw from your accounts.)
Sometimes it may make sense to withdraw from multiple account types in the same year. Other times, strategically realizing capital gains or drawing from a traditional IRA earlier in retirement may improve the long-term tax picture.
Your investment holdings matter, too. Qualified dividends, ordinary dividends, interest, capital gains, and certain investment distributions can all receive different tax treatment.
What your advisor should help you understand: A withdrawal strategy that considers your investments, tax situation, income needs, and future tax exposure, not simply which account has available cash.
The goal isn't necessarily to pay the least tax this year. It's to make thoughtful decisions about taxes and income over your entire retirement.
3. Should I Be Considering Roth Conversions Before Retirement?
For many pre-retirees, the years between leaving work and the start of RMDs (age 73 or 75, depending on your birth year) are worth evaluating for Roth conversions. Whether a conversion makes sense depends on your tax bracket, your Medicare costs, and the rest of your plan.
One strategy worth evaluating is a Roth conversion.
A Roth conversion moves money from a traditional retirement account into a Roth account. Generally, amounts that haven't already been taxed become taxable income in the year of conversion. In exchange, future qualified Roth withdrawals can be tax-free.
Why might that matter?
Imagine you've spent your working years contributing to traditional 401(k)s and IRAs. You've accumulated substantial savings, but most of that money will eventually be subject to income taxes when withdrawn.
Once RMDs begin, those required withdrawals could push your taxable income higher than expected.
A carefully evaluated series of Roth conversions before then may help manage future taxable retirement account balances. (Learn more about multi-year Roth conversion plans and whether you should do a Roth IRA conversion.)
But Roth conversions aren't automatically beneficial. The additional income can increase your current tax bill, affect Medicare premiums (see how Roth conversions can affect Medicare premiums), and have other unintended consequences.
What your advisor should help you understand: Whether Roth conversions make sense, which years might offer opportunities, how much to consider converting, and the potential effects on taxes and Medicare costs.
This is where retirement tax planning becomes especially important. A conversion decision shouldn't be made in isolation from the rest of your financial plan.
4. When Should I Claim Social Security, and How Does That Decision Affect My Other Income?
The right claiming age depends on your health, marital status, other income, and spending needs. Your advisor should show how different claiming ages change your total retirement income, portfolio withdrawals, taxes, and survivor benefits.
You can generally begin collecting Social Security retirement benefits as early as age 62. Waiting until your full retirement age (67 if you were born in 1960 or later) provides your full retirement benefit, and delaying beyond that age can increase your monthly benefit up to age 70.
But a larger monthly benefit doesn't automatically make delaying the right decision for everyone.
Your health, marital status, other income sources, spending needs, and financial resources all matter.
For married couples, the decision becomes even more important because claiming strategies can affect the benefit available to a surviving spouse.
And Social Security shouldn't be evaluated separately from your investments.
For example, delaying Social Security might mean withdrawing more from your portfolio during the early years of retirement. That could create additional tax-planning opportunities, but it could also expose your investments to greater withdrawal pressure if markets decline.
Claiming benefits earlier might reduce portfolio withdrawals, but it can also mean accepting a permanently reduced monthly benefit compared with waiting.
Part of your benefit may also be taxable. See how Social Security is taxed, or try our Should I Delay Social Security calculator.
What your advisor should help you understand: How different claiming ages affect your total retirement income, portfolio withdrawals, taxes, and potential survivor benefits.
The right answer depends on your circumstances. What's important is understanding the tradeoffs before making a decision.
5. Could My Retirement Income Decisions Increase My Medicare Premiums?
Yes, they can. Higher-income Medicare beneficiaries may pay extra for Part B and Part D through the Income-Related Monthly Adjustment Amount (IRMAA), and Medicare generally looks at your income from two years earlier.
This is one of the most commonly overlooked areas of retirement planning.
Many people assume Medicare premiums are generally the same for everyone.
They aren't.
Here's what makes this especially important for retirement planning.
Under the IRMAA two-year look-back rule, Medicare generally uses your income from two years earlier to determine whether these additional premiums apply.
That means a large Roth conversion, substantial capital gains, or other income recognized today could affect your Medicare premiums two years from now. You can see the income thresholds in our 2026 IRMAA brackets post.
For married couples, these additional costs can apply to both spouses.
Retirement itself may provide an opportunity to request a reduction in an IRMAA determination when income falls after leaving work. Work stoppage is one of the "life-changing events" the Social Security Administration recognizes on Form SSA-44. Learn more in how to appeal an IRMAA determination. Planning ahead is still valuable.
What your advisor should help you understand: Whether your projected income could trigger higher Medicare premiums, how investment and tax decisions might affect those costs, and what options may be available to manage them.
If you're retiring before age 65, your plan should also address how you'll obtain and pay for health insurance until Medicare eligibility.
Healthcare shouldn't be an afterthought in your retirement income strategy.
For a closer look, explore our Complete IRMAA Planning Guide.
The Bigger Question: Is Everything Working Together?
Notice something about these five questions?
They're connected.
- Your Social Security claiming decision affects how much you may need to withdraw from your investments.
- Your withdrawal strategy affects your taxable income.
- Your taxable income affects whether Roth conversions make sense and how much you may pay for Medicare.
- And your investments need to support all those decisions.
That's why retirement planning shouldn't happen one decision at a time.
At Sentient Financial, I use The Sentient System™, a coordinated approach that brings retirement readiness, income planning, investment management, tax planning, Social Security, and Medicare considerations together.
The idea is simple: When one part of your financial picture changes, we need to understand how it affects the others.
You can learn more about this approach on our How I Work page.
Already Have a Financial Advisor? Start With These Questions.
If you're already working with an advisor, I encourage you to bring these five questions to your next meeting.
A thoughtful advisor should be able to explain how these issues are being addressed in your plan, or outline how they would evaluate them.
You don't need someone who can predict the markets or guarantee a particular retirement outcome. You need someone who helps you understand your options, the tradeoffs involved, and how your financial decisions fit together.
And if your current advisor is already addressing all five areas, that's a positive sign.
But if you've mostly been discussing portfolio performance, market outlooks, and investment allocations, it may be worth asking whether there's more planning to be done.
You don't necessarily need a different portfolio. You may simply need a more complete perspective on your retirement.
Looking for more? Browse our full list of retirement planning questions every pre-retiree should ask, try the Retirement Readiness Calculator, or download the free Retirement Transition Field Guide.
Frequently Asked Questions
Ask how much income you will have after taxes, which accounts to withdraw from first, whether Roth conversions fit your plan, when to claim Social Security, and how your income could affect Medicare premiums through IRMAA. These decisions affect one another, so a coordinated plan can help you see the tradeoffs.
It depends. The best order may reflect your tax bracket, future required minimum distributions, how much of your Social Security is taxed, and your Medicare premiums. Some retirees draw from taxable accounts first, but that is not a universal rule, and drawing from several account types in the same year may make sense in some situations.
It can. The amount you convert generally counts as taxable income in the year of the conversion. Because Medicare generally looks at your income from two years earlier, a large conversion may raise your Part B and Part D premiums through IRMAA two years later. Results vary by individual situation.
Medicare generally uses your tax return from two years earlier to decide whether you pay an IRMAA surcharge. For example, income you recognize in 2026 may affect your premiums in 2028. If your income drops because of a life-changing event such as retirement, you may be able to request a new determination.
You can generally claim as early as age 62, at full retirement age for your full benefit, or as late as age 70 for a larger monthly benefit. The right choice depends on your health, marital status, other income, and spending needs, so it is worth reviewing alongside your withdrawals and taxes.
About Patrick Thompson: Retirement Planning in Laguna Niguel
I'm Patrick Thompson, AWMA®, founder of Sentient Financial, an independent, fee-only fiduciary financial advisory firm in Laguna Niguel, California. I work with pre-retirees in Laguna Niguel, Aliso Viejo, Mission Viejo, Dana Point, and San Clemente, and I work virtually with clients across the US.
I help professionals approaching retirement make sense of the transition from accumulating wealth to creating retirement income, with particular attention to how taxes, investments, Social Security, and Medicare decisions work together.
If you're wondering whether your existing retirement plan addresses all the important pieces, I'd be happy to have a conversation.
No pressure. No obligation to make changes. Just an opportunity to discuss where you stand and whether additional planning could be helpful.
Sentient Financial, LLC. Guiding you through your financial journey.
Important Disclosure: Sentient Financial, LLC is a state-registered investment adviser in California. This article is provided for educational and informational purposes only and is not individualized investment, tax, or legal advice. Tax laws, Medicare rules, and individual circumstances vary. Retirement planning strategies should be evaluated in light of your specific financial situation, objectives, and risks. Consult the appropriate qualified professionals before implementing tax or legal strategies.

Ready to See What a Clear Plan Could Look Like for You?
If you’ve got 20 minutes and want an honest conversation about your retirement income and tax picture, let’s find out if we’re the right fit.