Why I Wouldn't Sacrifice Retirement to Pay for College
Patrick Thompson
Quick note: This is my take as a dad and a financial advisor, not financial advice for your family. There's more than one way to approach this.
Every year around this time, the same conversation finds me. Dozens of them, actually. High school seniors are eyeing graduation, college decisions are getting real, and parents are doing the math. They want to help, but they'd also like to retire before they're 80.
That's why I'm writing this. With a 19-year-old son in college and a 15-year-old daughter in high school, college planning isn't just something I talk about with clients. It's a pretty regular topic around our own dinner table, too.
So I'm not exactly a neutral observer.
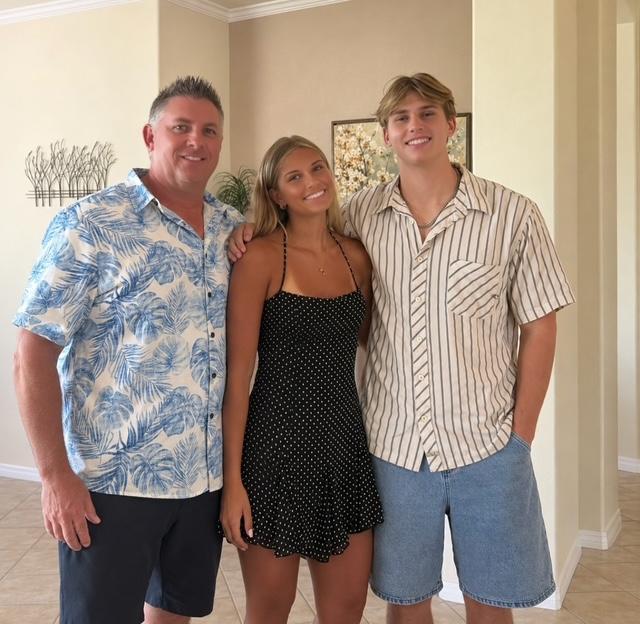
I put myself through college at Cal Poly SLO, right out of high school. Student loans, a job that was basically full time, and bills that did not care one bit about my final exam tomorrow. I wanted my kids to have a little more breathing room than I did.
That experience is also a big reason I got into this field. I wanted to understand money better than I did growing up, and I was pretty sure there were smarter ways to build a stable life. (Turns out there are. Who knew?)
Now that I'm on the parent side of the equation, I understand the emotional tug-of-war a lot better. You want to give your kids every opportunity. You also know that the retirement you've been saving for all these years isn't exactly getting cheaper.
So when I say I'm a big believer in community college, it comes from experience. I want my kids educated, and I want the price tag to make sense for the whole family.
Is the College Experience Worth the Price?
The financial return on a college education deserves a closer look than ever. With what some schools charge today, I don't think parents should automatically assume every degree, at every price, is a good investment.
The price and the opportunities it opens up have to add up together. For some graduates, that math simply doesn't work out the way they hoped.
Start with the price. If a student can knock out the general education and introductory courses at a much lower cost and still have them count toward the degree, I don't see that as a lesser choice. I see it as money well saved.
It also gives students room to figure out what they actually want to do. We ask 18-year-olds to pick a career for the next 40 years, and some of us can barely agree on where to eat dinner.
Some students are certain at 18 and feel differently at 20. Others have no idea yet. Both are fine with me. I'd just like the figuring out to come with a smaller bill.
And yes, I know. "But what about the college experience?"
For the record, I had my share of fun in college, even while working practically full time. My calendar wasn't all work shifts and exams. I want my kids to have that part, too.
There's also something to be said for learning to run your own life: buying groceries, getting to class on time, and discovering that clean clothes do not magically reappear in the drawer.
Laundry is an important life skill, and so is navigating a social life. I'm just not convinced either one takes eight semesters to learn.
Two years at a university after transferring offers plenty of chances to make friends and become independent. And when a transfer student finishes the requirements, they earn that university's degree. I care a lot more about what my kid learns and does with it than whether every class was on the same campus.
Now, a scholarship, a specific program, or a student's particular needs can make a four-year start the better fit. I'm not saying community college wins every time. I just think it deserves a lot more credit than it gets.
What About Saving for College?
Which brings up another question I hear a lot: Is a 529 college savings plan even worth it if you can't fund all four years?
I think so.
A semester counts. A year counts. Money set aside for qualified expenses after a transfer counts.
Start early, contribute when the budget allows, and don't worry that the account has to cover every textbook and cafeteria sandwich to be worthwhile.
And remember, 529 plans aren't limited to traditional four-year universities. They can also help cover eligible expenses at qualifying trade schools and certain other educational programs. There are even provisions for some K–12 expenses, subject to applicable rules and limits.
The point is that saving for education doesn't have to be an all-or-nothing proposition.
Where College Funding and Retirement Collide
Where I get uncomfortable is parents pulling money from retirement accounts or borrowing against their home to pay for college.
I understand the impulse. I just told you why I feel it myself.
But parents nearing retirement have fewer working years left to replace that money. Wanting to give our kids more than we had doesn't change that math, no matter how much we wish it would.
Here's the part I wish more parents would think about.
A $50,000 college expense isn't necessarily just a $50,000 decision when you're five or ten years from retirement. That money may have been intended to help fund another 20 or 30 years of living expenses.
And unlike college, there aren't scholarships or student loans available to finance your retirement.
Taking money from a retirement account can also create tax consequences, depending on the type of account, your age, and how the withdrawal is made. And borrowing against your home can mean carrying additional debt into retirement.
These aren't necessarily bad decisions in every situation. But they deserve a much bigger conversation than simply asking, "Can we afford the tuition?"
I'd rather see a student take on a manageable amount of debt than parents reach retirement unprepared, or working years longer than they wanted to.
And "manageable" is doing real work in that sentence.
I know firsthand that student loans aren't something to shrug off, and I'd never assume they're cheap or easy to repay. The amount borrowed should make sense relative to the student's likely career opportunities and ability to repay it.
For me, helping my kids means giving them a good start while keeping our own finances on solid ground.
That might be some savings, help with certain expenses, and a less expensive path to the degree. It doesn't have to mean paying for everything.
Helping Our Kids Without Sacrificing Our Future
After years of working with families approaching retirement, one thing I've come to appreciate is that financial decisions rarely happen in isolation.
Paying for college isn't just an education decision. It can also be a retirement decision, a tax decision, and sometimes even a decision about how much longer Mom or Dad needs to keep working.
And those trade-offs aren't always obvious when you're staring at a tuition bill.
That's why I feel so strongly about community college and exploring different educational paths before committing to a big price tag.
It's a way to give our kids opportunities without asking parents to hand over too much of their own future.
I want my kids to leave the nest. I just don't want either of us stuck with debt that wasn't necessary.
And I'd rather not end up moving into theirs later, either.
About the Author
Patrick Thompson, AWMA®, MBA, is the founder of Sentient Financial, an independent, fee-only fiduciary financial advisory firm. He helps individuals and families approaching retirement navigate retirement income, tax planning, and investment decisions. He's also a dad who understands that sometimes the most important financial decisions have very little to do with spreadsheets.
This article is for educational and informational purposes only and reflects the author's personal views. It is not individualized investment, tax, or financial advice. Education funding options, tax treatment, and retirement planning considerations vary based on individual circumstances.
Ready to See What a Clear Plan Could Look Like for You?
If you’ve got 30 minutes and want an honest conversation about your retirement income and tax picture, let’s find out if we’re the right fit.